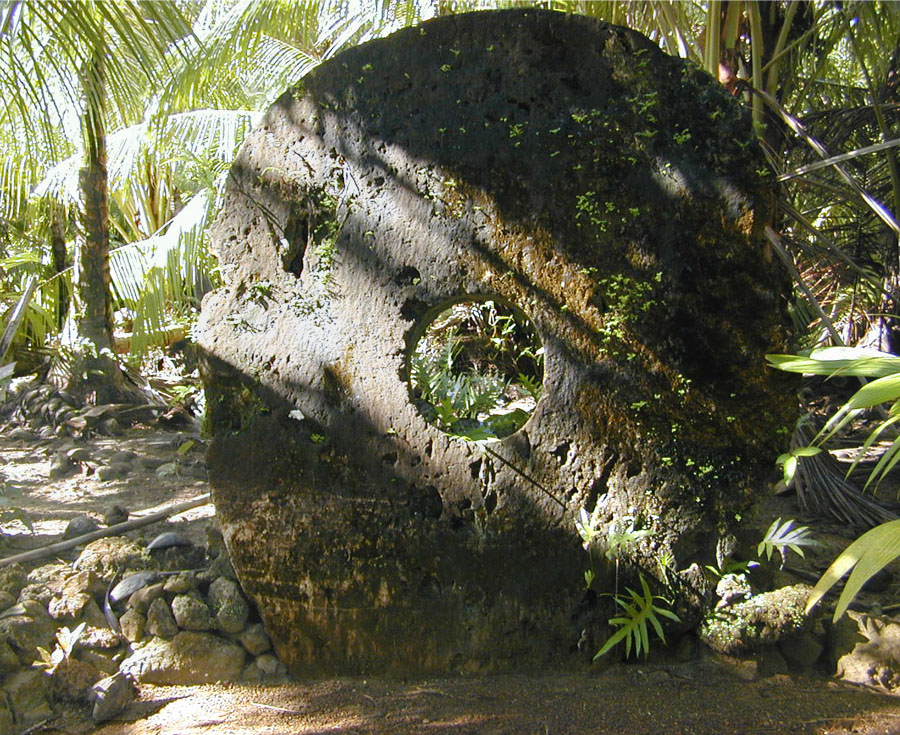
On the Pacific island of Yap, money was a stone. Not a coin or a note, but a limestone disc called rai, some as wide as a person is tall, far too heavy to lift. When a disc changed hands, nobody moved it. The islanders simply remembered, collectively, that ownership had passed. One famous stone, the story goes, sank to the bottom of the sea during a storm, and everyone agreed it still belonged to its owner and could still be spent. The money was never really the stone. It was the shared ledger in everyone’s heads.
I think about Yap whenever someone insists the digital euro is a “technical” question. Money has always been a social and political technology before it is a material one: a collective agreement about who owes what to whom, and who gets to keep the books. The debate over a retail Central Bank Digital Currency (CBDC) is usually framed as monetary plumbing. The more interesting questions are political-economic: how you design a digital euro determines how far it pulls deposits away from commercial banks, who keeps the ledger, and who ultimately pays for the change.
The core tension
The claim. A retail digital euro creates a direct structural pipeline for citizens to move money out of private commercial banks and into the ultimate safety of the European Central Bank (ECB). Without strict design guardrails, this triggers systemic bank disintermediation, hollowing out commercial banks and pushing the ECB into an accidental role as the eurozone’s primary credit allocator.
The evidence. When you deposit money in a traditional bank, that money becomes a liability on the bank’s balance sheet, the raw material it uses to fund loans, mortgages, and local growth. A digital euro quietly flips this. Central bank money carries zero default risk, so in any moment of economic anxiety the rational move is to flee to absolute safety. That instinct is the oldest reflex in banking. It is the queue outside the branch in It’s a Wonderful Life, when George Bailey begs his neighbours to understand that their money “isn’t here, it’s in Joe’s house, right next to yours.” A bank run is just disintermediation happening all at once. The fear with a digital euro is that it turns that desperate physical queue into a frictionless swipe, what economists studying the eurozone now call “fast” disintermediation, where deposits don’t trickle out but haemorrhage, forcing fire sales and making the very crisis everyone feared.
To prevent a permanent “digital bank run,” the ECB has built in guardrails: holding limits floated in the region of €3,000 per citizen, no interest paid on balances, and a reverse waterfall that automatically sweeps anything above the cap into a linked commercial account. The design is deliberately unattractive as a store of value: a wallet, not a savings vault.
Why it matters. Here is the paradox the guardrails expose. Make the digital euro too attractive, with high limits and interest, and it drains commercial banks, starves private lending, and centralises financial power in Frankfurt. Make it too restrictive, with low caps, no programmability and friction everywhere, and it becomes a ghost in the payments system, a solution to a problem citizens don’t feel, ignored in favour of the card in their pocket that already works perfectly well. The ECB is trying to thread a needle between irrelevance and instability.
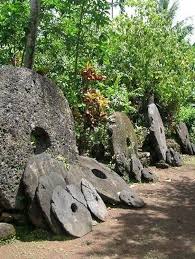
And this is where the Yap stones return. The deeper question isn’t the cap size. It is who keeps the ledger, and what they can see written in it. A recent OMFIF commentary put the citizen’s objection bluntly: the ECB can answer every “why not?” (it won’t hold your data, banks still intermediate, there’s no spending-control “programmable money”) and still have no convincing answer to “why bother?” The honest, awkward truth is that Europeans have so little payment privacy left to lose. Visa, Mastercard and PayPal already read and monetise the ledger; they have already cut people off. The digital euro doesn’t obviously worsen that. What it changes is whose hands the ledger sits in: a relatively accountable public institution rather than a foreign private duopoly. Whether that is reassuring or alarming is, fittingly, a political question, not a technical one.
The thing I keep coming back to
The digital euro isn’t really a new idea. It is the same negotiation the islanders of Yap, the depositors of Bedford Falls, and every central banker since have been having: between money as a public good you can always rely on, and money as private credit that fuels growth but can vanish in a panic. CBDCs just force the eurozone to write the terms of that bargain down, explicitly, in legislation, with the European Parliament’s vote expected this June. The design of the digital euro isn’t an engineering challenge. It is a profound political choice about the future architecture of European capitalism, and, as ever with money, about whom we trust to keep the books.
What I’m reading
If you want to follow the friction points between public sovereignty and private banking, these are the clearest views from the trenches:
- CEPR / VoxEU, “Demystifying fears about bank disintermediation”. The optimist’s case: Bofinger, Haas and others argue the reverse-waterfall-plus-holding-limit design defuses the run risk by construction. Read it against the Bundesbank’s more cautious modelling for the real debate.
- Deutsche Bundesbank, “Will the digital euro strengthen financial stability? Yes, within certain limits”. The cleanest statement of the “slow vs fast disintermediation” distinction, with a eurozone-calibrated model showing why an unlimited digital euro would net-worsen stability.
- OMFIF Digital Monetary Institute, “The digital euro approaches, but the ECB has gaps to fill”. The “why bother?” problem, stated sharply: a currency still missing both a citizen rationale and a defined win condition.
- Cato Institute, “The Digital Euro Isn’t About Freedom”. The libertarian objection, worth reading precisely because it’s hostile: it sharpens where the surveillance critique is strong and where it’s overblown.
- Peterson Institute (PIIE), “China gives up on state-backed digital cash”. The essential comparative case: the e-CNY’s redesign is the cautionary tale Europe is implicitly defining itself against.